Bank Fraud · Restitution
Who Receives Restitution in a Bank Fraud Case?
Restitution depends on the statute, the offense, who qualifies as a victim and the loss that remains after required credits.
Eligible to Practice in Texas
Attorney at Law
Bar Card Number: 00796807
TX License Date: 11/01/1996
214 Connally St Ste A
Sulphur Spgs, TX 75482-2612
The bank named in the indictment may receive restitution, but it is not necessarily the only recipient. Start with the statute governing the offense. The court must identify who qualifies for payment, determine the loss and apply any required credits. The records may also show that someone else compensated the victim.
Follow the loss and the later payments
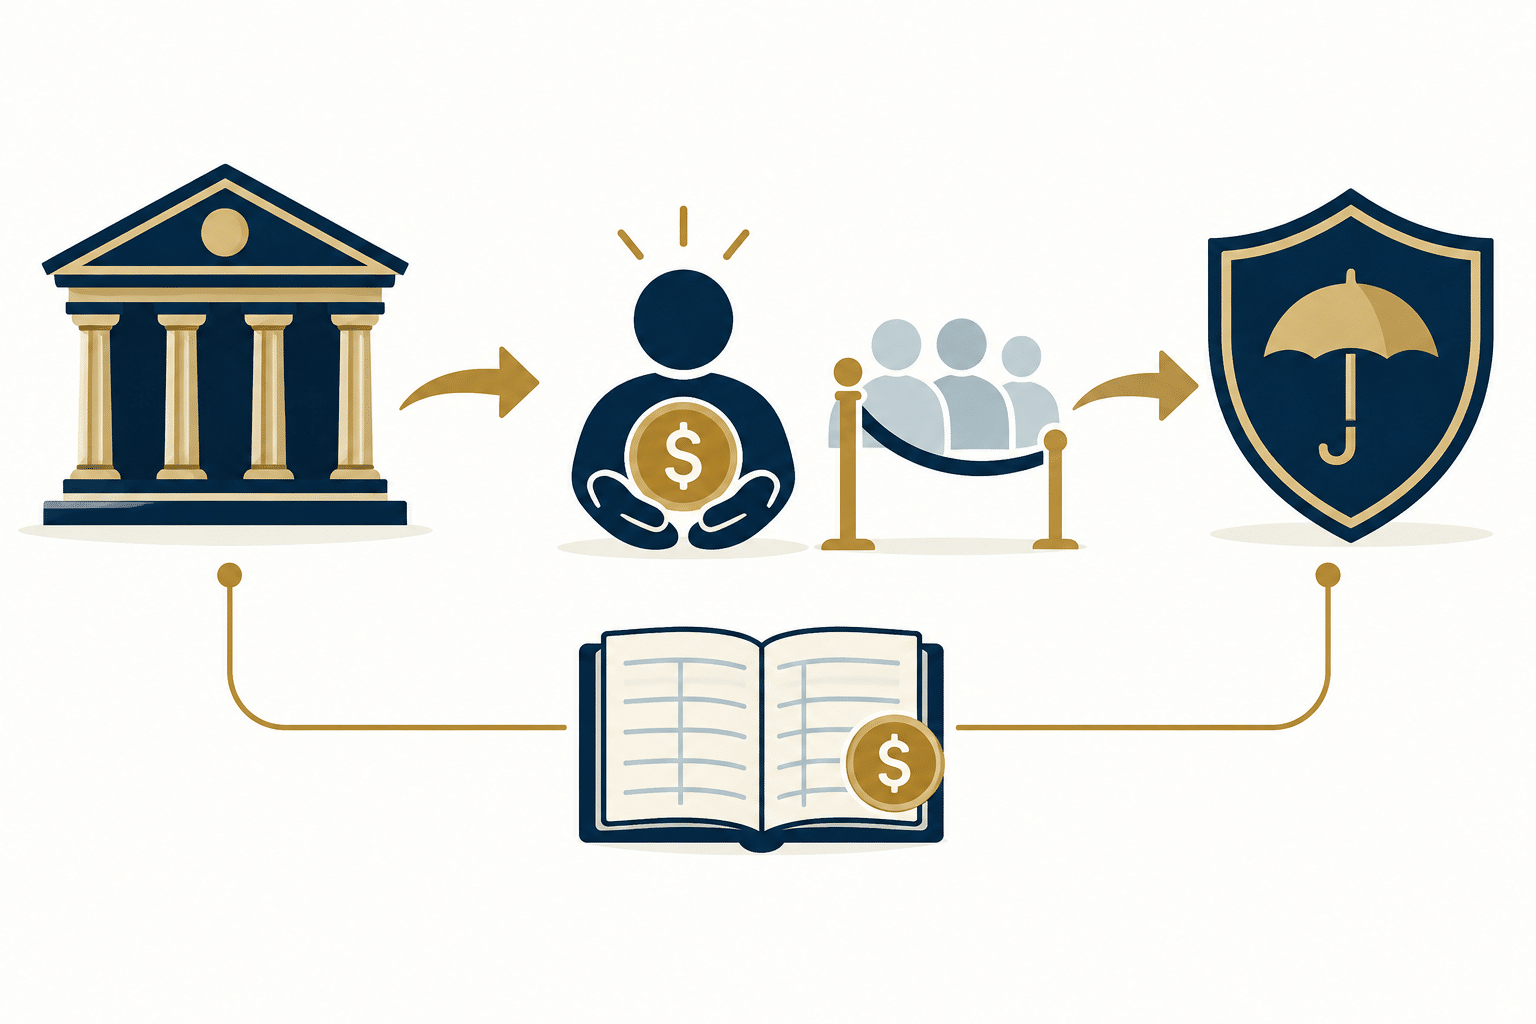
A loan can change hands before sentencing. There may be a guarantee, a payment to a customer, an insurance claim or a sale of collateral. Put those events in date order. The party that held the money at the start may not be the party left bearing the loss.
Insurance does not simply erase the defendant’s restitution obligation. Section 3664(f)(1)(B) says compensation from insurance or another source is not considered in determining the restitution amount. Section 3664(j)(1) addresses who gets paid: a provider that compensated the victim, or is obligated to do so, may receive restitution, but only after the victims receive the restitution owed to them under the order.
Consider a customer reimbursed by a bank, followed by an insurer’s payment to that bank. Trace each payment, keeping in mind that the records may all concern one original loss. Adding each ledger entry as a fresh loss would count the same money more than once.
Build a worksheet from the underlying records
For each disputed payment, record:
- The original transfer and who held the property.
- Any assignment or change in ownership.
- Reimbursements, recoveries and the balance still claimed.
- The document supporting the entry.
Give counsel the settlement papers too. A civil settlement or another payment may affect restitution, but the result depends on the governing rule and the facts. It should neither disappear from the review nor be treated as an automatic credit without analysis.
Check the proposed order against the offense
Changing the payee does not settle how much is owed. Counsel needs the offense of conviction, the plea or verdict and the proposed list of recipients. For each name, ask how the criminal conduct harmed that person. Section 3663A requires direct and proximate harm and contains a further provision for offenses involving a scheme, conspiracy or pattern. Read that provision with the actual scheme language in the case before deciding which losses belong in the order.
Use the bank’s regulatory schedule as an index to the records, then check it against:
- Payments credited to the loan.
- Proceeds from the collateral.
- Assignment documents.
- Compensation already paid.
At sentencing, identify the disputed entry and request the document that supports it. If the records contradict the proposed amount, explain that difference in the objection.
Related resources
Primary legal sources
- 18 U.S.C. § 3663A (mandatory restitution for covered offenses).
- 18 U.S.C. § 3664(f)(1)(B) and (j) (insurance, other compensation and payment priority).
To discuss representation, contact Heath Hyde or call 903-439-0000. Representation begins only after the firm agrees to take the matter.